Motorola Solutions (NYSE: MSI) ended its third quarter of 2026 with a record $16.6 billion backlog. Now that is a lot of orders to be fulfilled. But on November 16, 2026, Motorola Solutions stock sat at $534.17 a share. Using our forward earnings estimate, approximately 70% of that price is predicated on growth which has yet to occur. Therefore, the only question that matters for Motorola Solutions stock is not “Is business good?” It clearly is. The question is whether Motorola can make enough profit on all those orders to justify today’s price.
What Does Motorola Solutions Do?
First, a common mix-up behind searches for “Motorola company stock.” Motorola Solutions isn’t the phone company. Lenovo is the owner of Motorola Mobility, which manufactures Motorola phones. When you purchase MSI stock, you’re not wagering on phones.
When things go wrong, emergency workers and organizations rely on the tools provided by Motorola Solutions. It makes money in three main ways:
- Communications networks and radios. They are the “mission-critical” systems police, firefighters and paramedics employ. Mission-critical simply translates to lives are on the line and the system must not fail.
- Video security and access control. Consider cameras and the systems that determine access to which door.
- Command center software. This is how the software is used by dispatchers when they receive calls and dispatch help.
It serves the private sector, public safety agencies, and governments. It makes two types of profit: first, when it supplies the equipment and, after, from the services and software that keep it running for years.
In fact, that loyal and adhesive client base is one big reason that investors love this company. Agencies aren’t changing their radio networks for no particular reason. When a county develops its emergency system around Motorola equipment, it is difficult and expensive to change, and dangerous. That loyalty is the reason many people consider Motorola Solutions stock to be a “boring in a good way” kind of investment. However, steady and low cost are two different things.
What Does Motorola’s $16.6 Billion Backlog Tell Investors?
The backlog is the value of orders that a company has received but not yet fulfilled. It is similar to a bakery that received a number of orders for cakes next month. The funds haven’t been deposited in the register, but you expect they will be.
Motorola provided three numbers that are related. They nest like the boxes:
| Company disclosure | Amount | What it means in plain English |
| Q3 2026 ending backlog | $16.6B | All orders waiting to be filled — up 14% from a year earlier |
| Remaining performance obligations | $10.0B | A narrower accounting count of work still owed under contracts as of October 3, 2026 |
| Expected revenue within 12 months | $4.4B | The part of that $10.0B the company expects to count as sales over the next year |
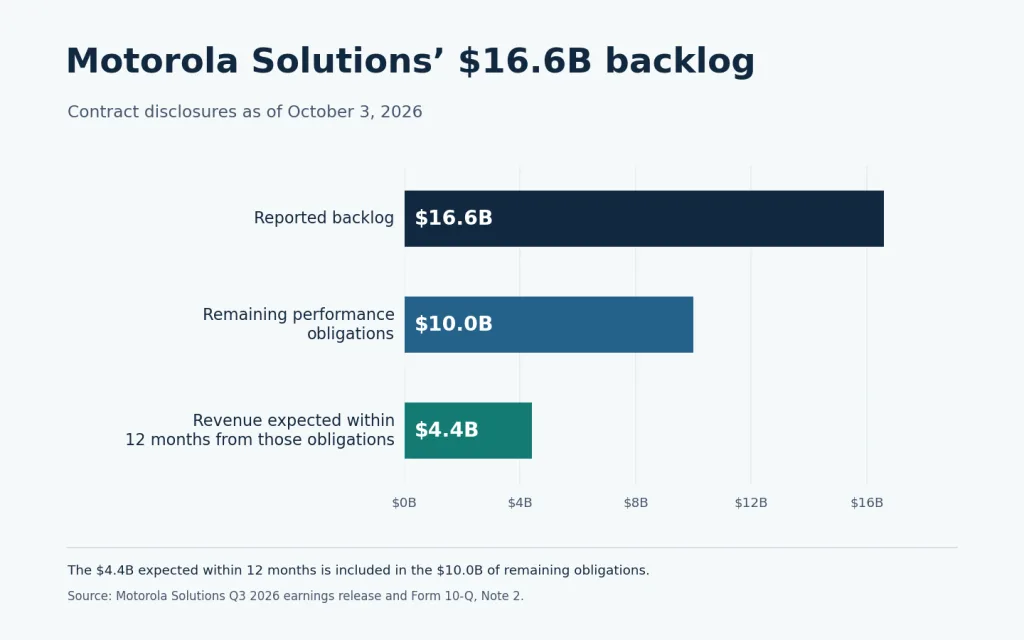
Bar chart showing Motorola Solutions’ $16.6B backlog, $10.0B remaining performance obligations and $4.4B revenue expected in the next 12 months.
Why is the second number a lot smaller than the first? Remaining performance obligations are counted under strict accounting rules. For some software and services customers, they have the option of canceling their contracts. If that’s permitted, the accounting only counts the shorter, non-cancellable portion of the deal. So the backlog is the big picture. The figure for the obligations is conservative.
Here is the catch investors should be aware of. An order does not equal revenue and revenue does not equal cash. Cash arrives when each contract’s payment terms say it is due. Our Super Micro stock analysis also examines how orders, inventory, and customer payments affect cash flow.
But the monetary landscape was a little bit less sunny. Free cash flow is the cash remaining after a company pays their bills and invests in their business. The third quarter’s sales grew 12%, while the free cash flow available to the company was $589 million, compared with $733 million a year ago. Management said higher tax and interest payments were to blame. The free cash flow for the first nine months amounted to $1.39 billion, while the previous year’s figure was $1.43 billion.
Free cash flow can fall even while sales rise — our Amazon vs Apple comparison shows a case where it turned negative.
That isn’t alarming. Despite that, sales still increased and the company still generated more than a billion dollars in free cash flow. However, it’s a reminder that a large order book doesn’t necessarily translate to filling the bank account.
Our ASML vs Broadcom analysis looks at two more companies with huge backlogs — and the same question of whether the orders turn into cash.
Why Did Motorola’s Return on Operating Assets Fall?
So, there’s the part that makes the story more interesting.
Suppose that a friend owns a food truck. One truck earns her $50,000 a year. Then she purchases another truck. Sales increase but not by a factor of two. Although the business is larger, her income per truck decreases.
Vaguely that’s what happened at Motorola.
We measure this with return on net operating assets (RNOA). It measures the profit a company makes per dollar invested in the business. RNOA is the result of the combination of two simple elements:
- After-tax operating margin: the percentage of profit per dollar of sales after taxes.
- Operating asset turnover: the number of dollars of sales that the company can generate from a dollar of operating assets.
RNOA can be calculated by multiplying the two. We use the same margin and asset turnover breakdown in our Amazon vs Nvidia stock comparison to explain how each business earns a return on its operating assets.
| First nine months | 2025 | 2026 | Change |
| After-tax operating profit margin | 20.19% | 18.46% | −1.73 points |
| Operating asset turnover | 1.42× | 0.84× | −0.58× |
| Return on net operating assets | 28.67% | 15.44% | −13.23 points |
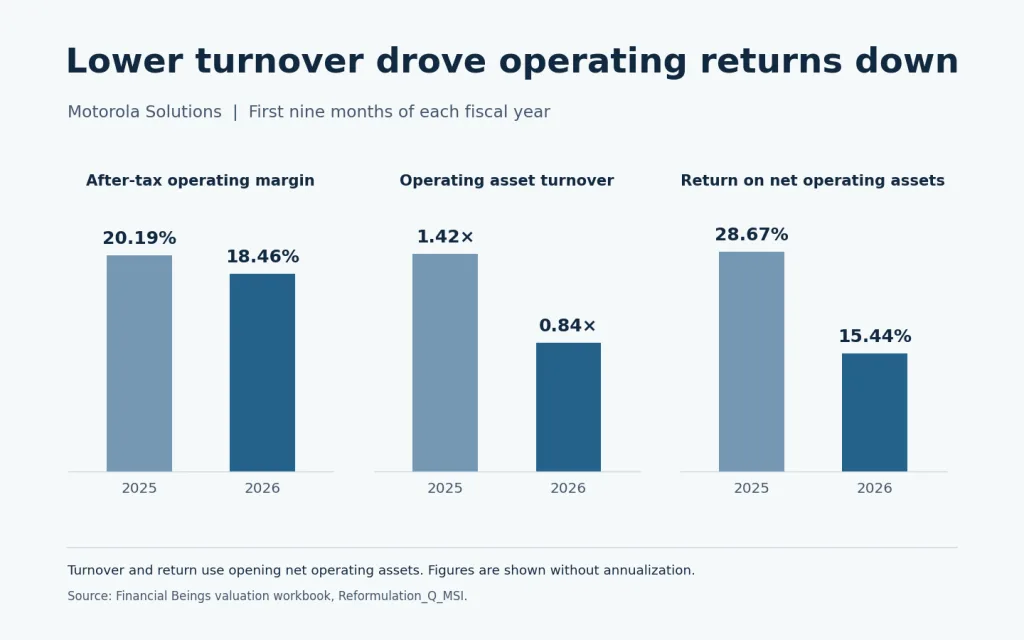
Three bar charts showing Motorola Solutions’ after-tax operating margin, operating asset turnover and return on net operating assets for the first nine months of 2025 and 2026
The margin was slightly reduced. Turnover declined significantly. The actual story is that. Motorola is now getting much less return for every dollar tied up in its operations.
Motorola’s opening net operating assets, a measure of the cash invested in the business’s operations, increased from $5.85 billion to $11.03 billion. In the same nine months, sales increased 11.1% to $9.22 billion. The after-tax operating profit was up only 1.6% to $1.70 billion.
So the business grew and grew on the balance sheet but sales and profits lagged behind. Motorola was like the food truck owner, and purchased additional “trucks.” One was the Silvus acquisition that was completed in August 2025. This year’s comparison looks harsher because the 2025 starting balance predates that deal.
Is that bad? Not necessarily. Acquisitions may not begin to pay off for a period of time. But it raises the bar. Motorola has to make a profit on a much bigger asset base now.
What Growth Is Priced Into MSI Stock?
The tension is at its highest here.
The price of each stock carries a silent prediction for the future. The quickest path to observing that guess is to pose the question, what would be the value of this business if it were not to grow at all? The amount in excess of that number is market compensation for growth.
| Financial Beings model output | Result | Basis |
| Market reference price | $534.17 | November 16, 2026 |
| No-growth value per share | $124.78 | FY2025 operating earnings |
| No-growth value per share | $160.44 | Forward operating earnings estimate |
| Share of price tied to future growth | 69.96% | ($534.17 − $160.44) ÷ $534.17 |
| Break-even growth | 7.88% | Perpetual growth in residual operating income, FY2025 base |
Given our forward earnings calculation, MSI would have a zero growth value of ~$160 per share. The stock was at $534. That is almost 70% of its price that is a gamble on the future. Our Google intrinsic value analysis applies the same question to Alphabet and Microsoft, examining how much future growth their share prices require.
What percentage amount of growth is needed on that bet? The answer starts with residual operating income. It’s the after-tax operating profit remaining after a charge for the capital the business uses, such as the amount remaining after you pay your rent from your paycheck.
With the investor’s desired 10% annual return based on our FY2025 figure, that residual operating income would have to increase by 7.88% annually for all eternity to support $534.17.
If you want to check growth rates yourself, our guide explains how to find the growth rate of a stock, step by step.
The value fluctuates significantly with small changes in that growth rate:
| Perpetual growth in residual operating income | Modeled value per share |
| 5.0% | $234.53 |
| 7.0% | $381.09 |
| 7.5% | $454.38 |
| 8.0% | $564.30 |
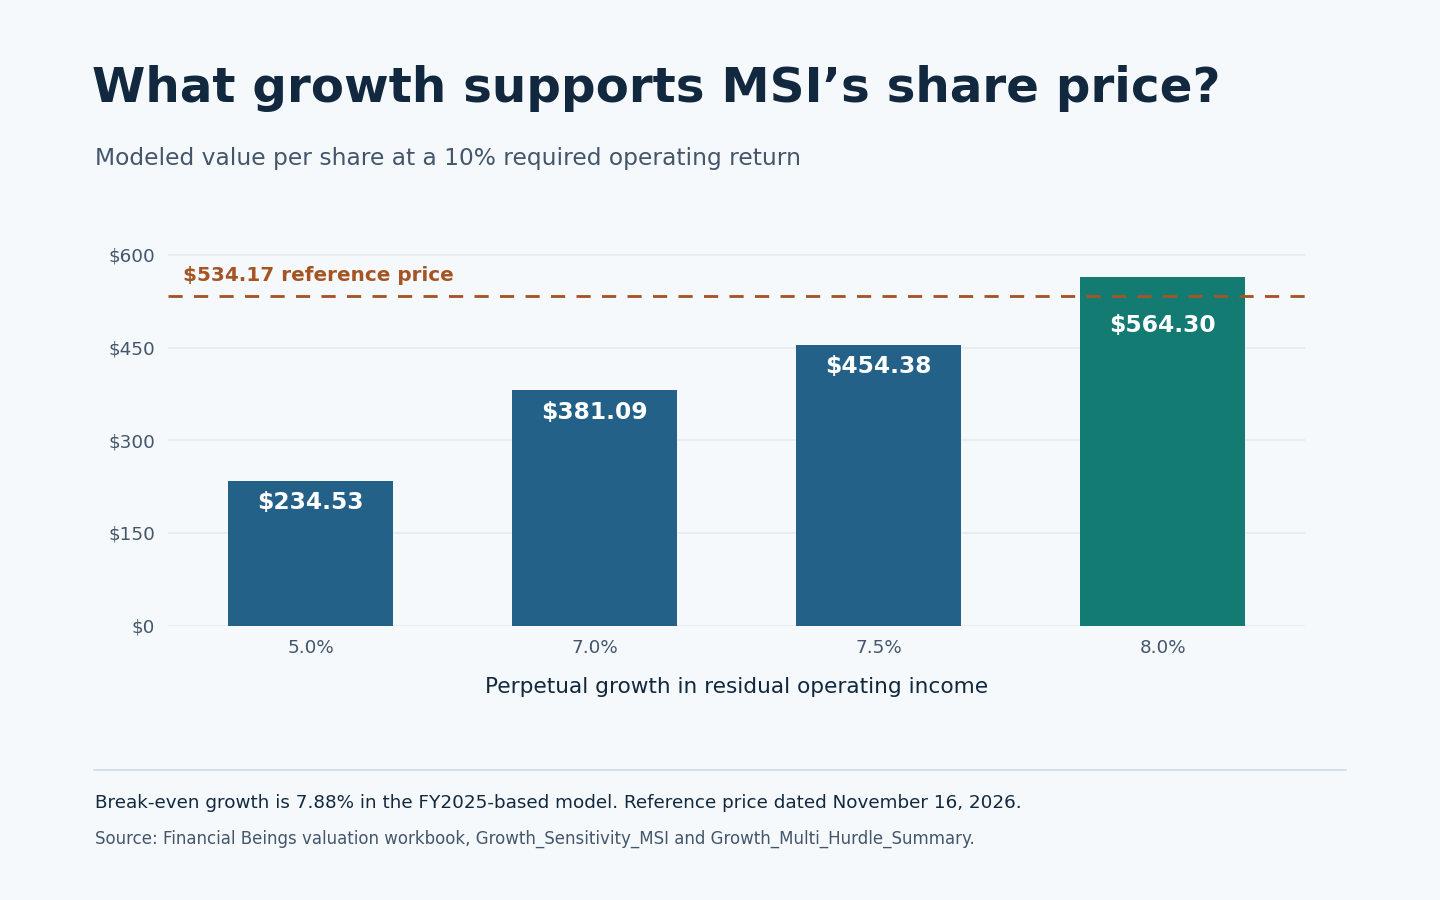
Bar chart of MSI’s modeled value per share at 5%, 7%, 7.5% and 8% perpetual growth rates as compared to the $534.17 price reference.
Notice the increase from 7% to 8%. That one point lifts modeled value by approximately $183 per share. That’s the degree of sensitivity of Motorola Solutions stock to long-term expectations. Our Netflix intrinsic value analysis shows another example of how small changes in assumed long-term growth can substantially change modeled value.
These are scenarios, not forecasts. They do not tell you what will happen, they tell you what you must believe. They put the stakes on the table, though. The math gets tight quickly when growth falls short.
What Could Change the Valuation in 2027?
Where, then, does Motorola stand?
This is a real order book. The customers are loyal. But the price already assumes Motorola will continue growing for a very long time. For that price to be justified, there are a few things that would help:
- Stronger organic growth. Not from acquisitions, that’s growth from the base business.
- Better operating margins. Retention of a higher percentage of each sales dollar.
- Higher asset turnover. Extracting more sales from that larger base of assets.
- Productive acquisitions. Deals such as Silvus should increase returns, not just size.
As part of the third-quarter conference call, management offered a preliminary estimate of about $14.25 billion in 2027 revenue. Plans are subject to change, so rely on the most up-to-date guidance before relying on this number.
Finally, the backlog of $16.6 billion indicates that demand is healthy. It doesn’t indicate if Motorola will make sufficient money on its bigger business to justify the price. That is the question to watch for anyone who owns or desires Motorola Solutions stock.
Motorola’s radios work great. That remains to be seen as to whether that stock will perform just as well.
FAQs
Is Motorola Solutions the same as Motorola phones?
No. Motorola Solutions is known as MSI and is engaged in supplying public safety radios, video security and command center software. Lenovo owns Motorola Mobility, the phone maker.
What is Motorola’s backlog?
It’s the value of orders that are received and not yet fulfilled. At the end of Q3 2026, it was a record $16.6 billion, up 14% from a year earlier.
Does the backlog guarantee future revenue?
Not entirely. There are total remaining performance obligations of $10.0 billion, with Motorola anticipating $4.4 billion of this to be converted into revenue within 12 months. There are some contracts that may be canceled.
Why did Motorola’s returns fall in 2026?
Primarily due to a nearly doubling of the operating assets after the Silvus deal, while sales rose only 11.1%. RNOA fell to 15.44% in the first nine months as each dollar of assets produced fewer sales.
Is Motorola Solutions stock overvalued?
It depends on what growth you expect. According to our model, $534.17 is justified only by 7.88% growth in residual operating income forever. In other words, if you expect less growth than that, you feel it’s overpriced.